The Mirage of Covered Calls: Sophistication or Sedation?
September 11, 2026
Covered calls are often presented as the thinking investor’s income strategy, combining stock ownership with option premium in a package that appears conservative, disciplined, and almost too sensible to question. Yet the strategy becomes considerably less attractive when investors focus exclusively on the premium while ignoring what they surrender in exchange for it, because every call sold against a position represents a decision to exchange some future upside for immediate income. The question is therefore not whether covered calls work, because they clearly can, but whether the income received adequately compensates the investor for the upside being transferred away.
That distinction is frequently overlooked because the premium arrives immediately, while the opportunity cost remains invisible until the stock makes the move the investor hoped for. A stock can sit still and make the covered-call strategy look brilliant, or it can fall sharply and make the premium look almost meaningless, while a powerful upside breakout can reveal the real cost because the investor has deliberately capped participation above the strike. The strategy is not inherently flawed, but using it mechanically can turn a potentially powerful portfolio into one that is optimized for income while being poorly positioned for growth.
Premature Victory: The Trade That Rewards You for Giving Up Upside
When you sell a covered call, you are effectively saying that you are willing to sell the stock at the strike price if the market moves above it before expiration. That can be entirely rational when the strike represents a price at which you are genuinely willing to exit, but it becomes problematic when the investor sells calls simply because the premium looks attractive. The danger is subtle because the premium feels like additional income, while the surrendered upside remains hypothetical until the market suddenly makes it very real.
Suppose you own a stock at $100 and sell a $110 call for $4. If the stock remains below $110 at expiration, you keep the premium and the shares, which can be an attractive outcome when the position was already expected to remain relatively range-bound. If the stock explodes to $140, however, your upside from the shares is effectively capped around the strike, and the $4 premium provides little consolation for the $30 of additional appreciation you surrendered. This is why covered calls should never be evaluated simply by asking how much premium they generate. The better question is what the investor is giving up to receive that premium.
The Crowd’s Approval Is Not the Market’s Consent
Covered calls have become popular partly because they offer something investors find psychologically attractive: visible income. Receiving premium today feels concrete, predictable, and controllable, while future capital appreciation is uncertain, which naturally appeals to investors who have become more concerned with generating cash flow than maximizing participation in long-term growth.
That psychological attraction can become dangerous when income itself becomes the objective. Recency bias, loss aversion, and the desire to feel productive can encourage investors to sell calls repeatedly even when the underlying stock is entering a powerful bullish phase. The portfolio begins producing small, regular rewards, and those rewards can create the illusion that the strategy is improving performance when the investor may actually be sacrificing the larger moves that drive long-term wealth creation. The premium becomes the dopamine and the opportunity cost becomes invisible.
Better Tweaked Than Abandoned
There is a more intelligent way to approach covered calls, and it begins by recognizing that the strategy can be useful when the investor is genuinely comfortable selling the underlying at the selected strike. Instead of selling calls automatically every month, the investor can become selective, using them when valuation appears stretched, sentiment becomes euphoric, momentum reaches an extreme, or the investor already has a predetermined exit level.
This changes the psychology completely because the call is no longer being sold merely to manufacture income. It becomes part of a larger capital-recycling process in which the investor is willing to surrender some upside because the probability of taking profits at the strike has become attractive.
An investor can also use a portion of the premium to maintain upside exposure through longer-dated calls, although this introduces additional option risk and should not be treated as a free replacement for the upside that was sold. The objective is not to create an infinitely clever options structure, but to avoid becoming so focused on current income that future opportunity disappears from the equation.
Tactical Clarity: The Real Play Is Not the Income
Covered calls make the most sense when the investor has a reason to want the stock called away. If the stock is dramatically overextended and you would happily exit at the strike, collecting premium while waiting for that outcome can be rational. If you remain extremely bullish and would be disappointed to lose the shares after a major breakout, selling the call may be completely inconsistent with your actual conviction.
This is where technical analysis becomes useful. RSI, MACD, moving averages, volatility, breadth, and price extension can help determine whether a position is becoming stretched, although none of these indicators should be treated as a mechanical signal to sell calls. The purpose is to identify conditions in which the probability of giving up substantial upside appears lower than the value of the premium being collected. The market does not reward activity for its own sake. It rewards decisions that improve the relationship between risk, reward, timing, and opportunity cost.
The Discipline of Stillness
The biggest mistake with options is assuming that because a strategy can be repeated every month, it should be repeated every month. Covered calls and cash-secured puts are tools, not obligations, and the fact that an option can be sold today does not mean today’s market provides a compelling reason to sell one.
The professional advantage is often the ability to wait for conditions that improve the economics of the trade. When a stock becomes euphoric and technically extended, an investor who is already willing to sell may find covered calls attractive, while periods of panic can create unusually rich put premiums on quality stocks that the investor genuinely wants to own.
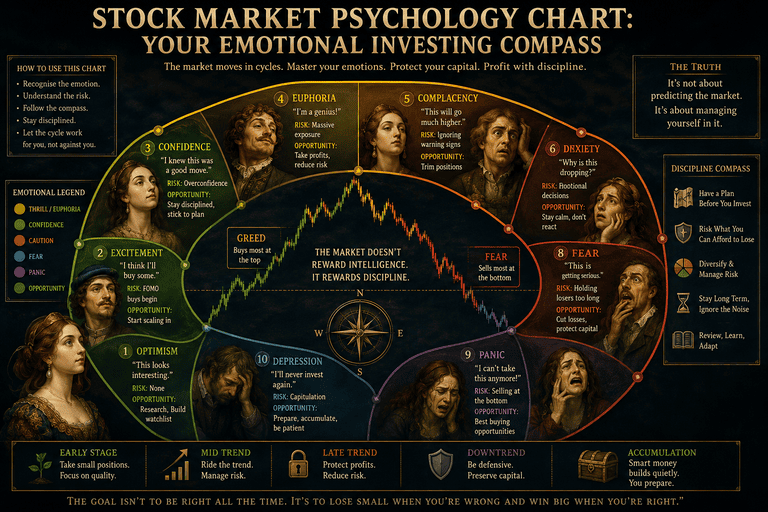
This creates a useful symmetry between the two strategies. Covered calls can be used when optimism becomes excessive and you are comfortable recycling the shares, while cash-secured puts can be used when fear becomes excessive and you are comfortable acquiring the stock at the strike price. The objective is not constant option income. The objective is capital recycling at favourable points in the emotional cycle.
The Tao of Two Trades
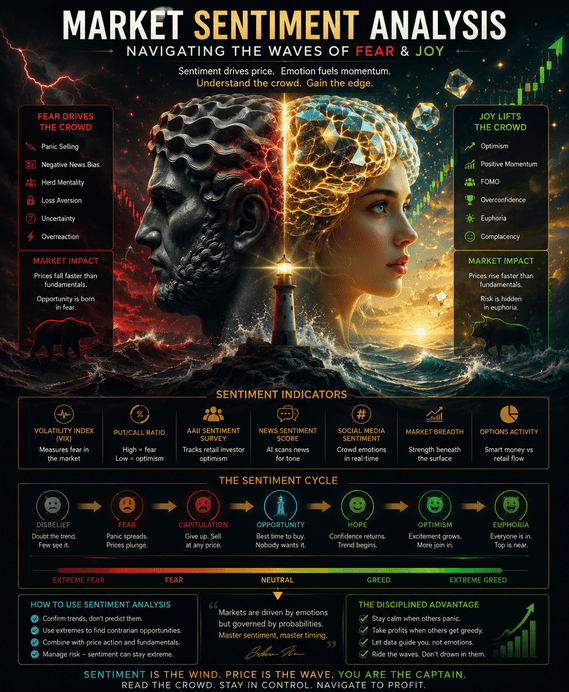
The pairing becomes particularly powerful when viewed through market psychology rather than option mechanics alone. Euphoria encourages investors to pay increasingly high prices because recent gains create confidence, while panic encourages them to accept increasingly low prices because recent losses create fear, and both extremes can create opportunities for an investor who has already decided what assets are worth owning.
That is where patience becomes an investment strategy rather than merely a personality trait. You do not need to sell calls because it is Tuesday, and you do not need to sell puts because implied volatility happens to be elevated, because the strongest opportunities usually appear when the emotional conditions of the market create a meaningful imbalance between price and value.
The rhythm is familiar: excess, recoil, stabilization, recovery, and eventually another round of excess. The investor’s job is not to control that rhythm but to recognize where the risk-reward equation becomes unusually favourable.
Illustration from the Edge
Imagine a momentum stock trading at $100 after a rapid rally, with RSI at 78 and the price substantially extended above its longer-term moving averages. You already believe $110 represents an attractive exit price, so instead of simply waiting for the stock to reach that level, you sell a $110 covered call and collect a premium.
If the stock remains below $110, you retain the premium and the shares, while if it rises through $110, the shares are called away at a price you had already deemed acceptable. Now suppose the stock subsequently falls sharply and fear pushes put premiums higher, while the underlying business remains attractive enough that you would gladly own it at $90.
A cash-secured put at an appropriate strike can potentially allow you to collect another premium while establishing a lower acquisition price if assigned. The same capital can therefore participate on both sides of the emotional cycle, first harvesting excessive optimism and later exploiting excessive pessimism. That is not about predicting every tick. It is about making the crowd’s emotional extremes work for you.
The Strategic Patience That Separates Investors From Traders
You do not need to sell options every week to be sophisticated. In many cases, the sophistication lies in knowing when the premium is simply not worth the opportunity cost, when the stock’s upside potential is more valuable than the income, and when the emotional conditions of the market have created a far better setup.
Blindly selling covered calls can create a portfolio that produces attractive-looking income while systematically limiting participation in its strongest winners. Used selectively, however, covered calls can become a legitimate tool for harvesting stretched valuations, generating cash flow, and recycling capital into better opportunities. That distinction separates strategy from routine. A strategy responds to conditions, while a routine responds to the calendar.
Final Word: Choose the Trade, Not the Yield
The real danger of covered calls is not the strategy itself but the seductive simplicity of the premium. Investors see cash arriving in their accounts and can easily conclude that they are being paid for doing nothing, while the market is quietly charging them through capped upside, assignment risk, and the possibility that the underlying stock falls far more than the premium can offset.
There are legitimate reasons to sell a covered call, particularly when you genuinely want to exit at the strike, when the position has become excessively extended, or when income generation is more important to you than maximizing upside participation. There are equally legitimate reasons not to sell one, especially when you remain strongly bullish and believe the stock could experience a substantial expansion in value.
The sophisticated investor therefore asks a different question. Am I being adequately compensated for giving away this upside? That question forces the premium back into its proper context. Income is only valuable when the opportunity cost is acceptable, and a strategy that generates small amounts of income while repeatedly surrendering large gains is not necessarily conservative, it may simply be quietly expensive.
The broader edge comes from three principles: tactical flexibility, because no single options strategy deserves permanent allegiance; strategic patience, because the best trades often appear when emotional extremes distort pricing; and capital recycling, because the objective is to continuously move capital toward the most attractive risk-reward opportunities rather than remain attached to one position or one strategy. Covered calls can be part of that architecture, but they should never become the architecture itself.
Interesting Insights